Empathetic interactions are the strategic advantage in P&C.
In property and casualty insurance, customer relationships are shaped at the moments that matter most, often during stress, loss or uncertainty. Whether it is an auto accident, property damage or a mortgage-related coverage issue, policyholders expect fast resolution, clear communication and genuine empathy.
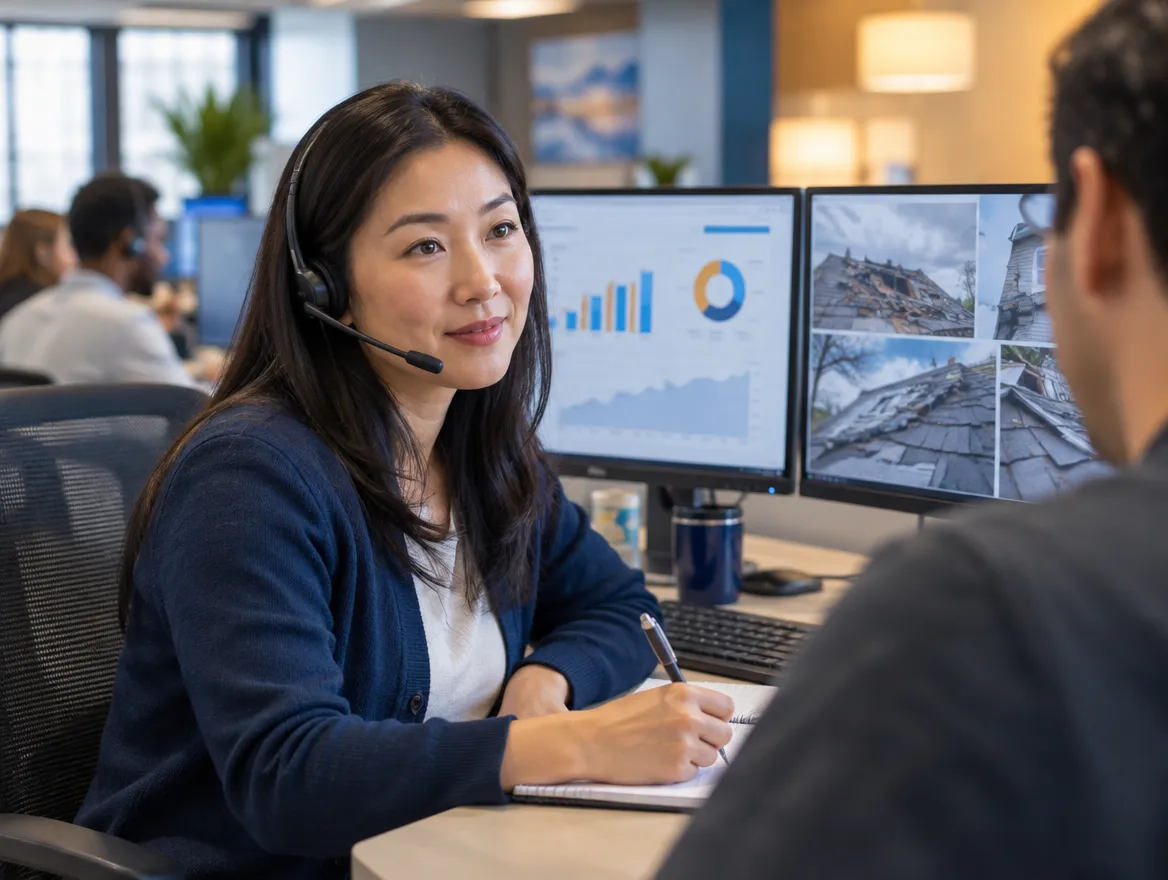
For today's P&C carriers, managing the full policy servicing lifecycle, from First Notice of Loss (FNOL) to claims adjudication, policy administration and subrogation, requires precision, regulatory discipline and human-centered engagement. Fusion CX delivers that balance through a specialized P&C insurance processing call center and end-to-end insurance BPO services designed for the sector's complexities.
Unlike generic contact centers, we operate with deep domain expertise across auto insurance, mortgage insurance, property insurance and specialty lines, backed by risk data collection for underwriters. Every program is built to reduce operational friction, maintain strict compliance and make each policyholder interaction a trust-building experience.
What we help you achieve
Reduced average handle time and shorter claims cycle times without sacrificing regulatory rigor
Higher policyholder satisfaction through timely, accurate responses on every channel
Fewer handling errors and lower risk, with adherence to NAIC and state-level regulations
A more skilled, engaged claims workforce that scales with your operations
One operating model from the loss report to recovery.
Property and casualty work crosses many teams. Here is how we keep claims, policies and recoveries connected.
01
Line-by-line playbooks
Before go-live we map each line of business, jurisdiction and escalation path, so agents know coverage limits and state rules for every call.
02
FNOL and adjuster coordination
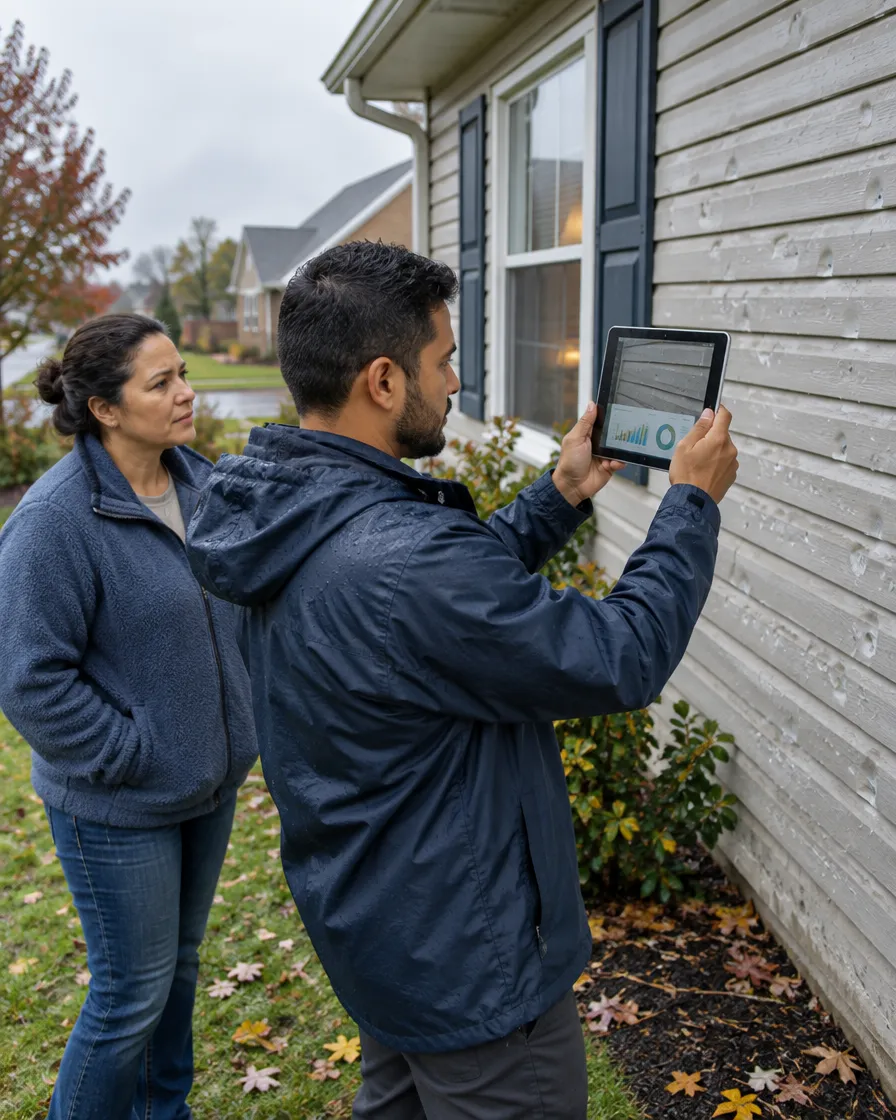
Loss details captured and validated at first notice, then status updates, pending requirements and follow-ups coordinated between policyholders and adjusters.
03
Suspicious claims and subrogation
Designated fraud indicators documented and escalated, while subrogation files get information gathering, documentation follow-up and regular case updates.
04
Policy servicing and QA
Endorsements, renewals and billing questions processed against your workflows, with every interaction checked for accuracy and state-level compliance.
Technology-enabled quality and compliance
AI that keeps P&C claims accurate and compliant.
Omind AI products give continuous oversight across claims and policy servicing, while your adjusters own every coverage decision.
How can a BPO provider support First Notice of Loss (FNOL) for P&C insurers?
A P&C insurance BPO can manage FNOL intake by capturing loss details, validating policy information, documenting incident information and routing claims to the appropriate teams. Trained representatives also give policyholders clear next steps and coordinate follow-up, helping insurers establish accurate claims records from the start of the claims journey.
Can P&C insurance BPO teams coordinate claims with adjusters?
Yes. Outsourced teams can provide claims status updates, coordinate information between policyholders and adjusters, track pending requirements and support routine follow-ups. This reduces communication gaps and lets adjusters spend more time on assessment and decisions while customers keep receiving timely updates.
What policy administration tasks can P&C insurers outsource?
P&C insurers can outsource enrollment support, renewals, policy modifications, endorsements, coverage inquiries and related administrative work. BPO teams process requests against insurer-defined workflows, update relevant systems, communicate changes to policyholders and escalate exceptions that need underwriting or other specialized review.
How can outsourced P&C insurance support improve claims cycle times?
Dedicated claims support teams reduce administrative delays by capturing accurate information at FNOL, following up on outstanding documentation, coordinating with adjusters and providing timely status updates. Standardized workflows and claims technology improve information visibility, so routine claims activities move forward with fewer avoidable delays.
Can a P&C insurance BPO support fraud detection and suspicious claim handling?
Yes. BPO teams can identify designated indicators, document suspicious activity, gather relevant claim information and escalate cases according to insurer-defined procedures. Technology-enabled monitoring adds visibility into claims activity, and specialized teams make sure potential fraud cases receive appropriate review rather than being handled as routine claims.
Can P&C insurance outsourcing support subrogation operations?
Yes. Outsourced teams can support the administrative and customer-facing side of subrogation, including information gathering, documentation follow-up, case updates and coordination with relevant parties. This keeps case workflows organized and adds capacity, while your internal specialists retain responsibility for complex decisions and recovery strategies.
How can P&C insurers maintain regulatory compliance when outsourcing?
Insurers can embed regulatory requirements into agent training, operating procedures, quality checks, escalation protocols and interaction monitoring. A specialized P&C BPO should align its workflows with applicable state-level and industry requirements, and technology-enabled quality monitoring adds oversight that identifies deviations needing corrective action.
How can outsourced P&C customer service improve the policyholder experience?
Specialized insurance representatives provide timely help with policy, billing, coverage and claims inquiries by voice, email and chat. Consistent information and clear next steps matter most during stressful events such as property damage or accidents, and that mix of accessibility, accuracy and empathy strengthens the overall policyholder experience.